Is Your Medicare Plan DPC-Friendly? A Doctor’s Scorecard

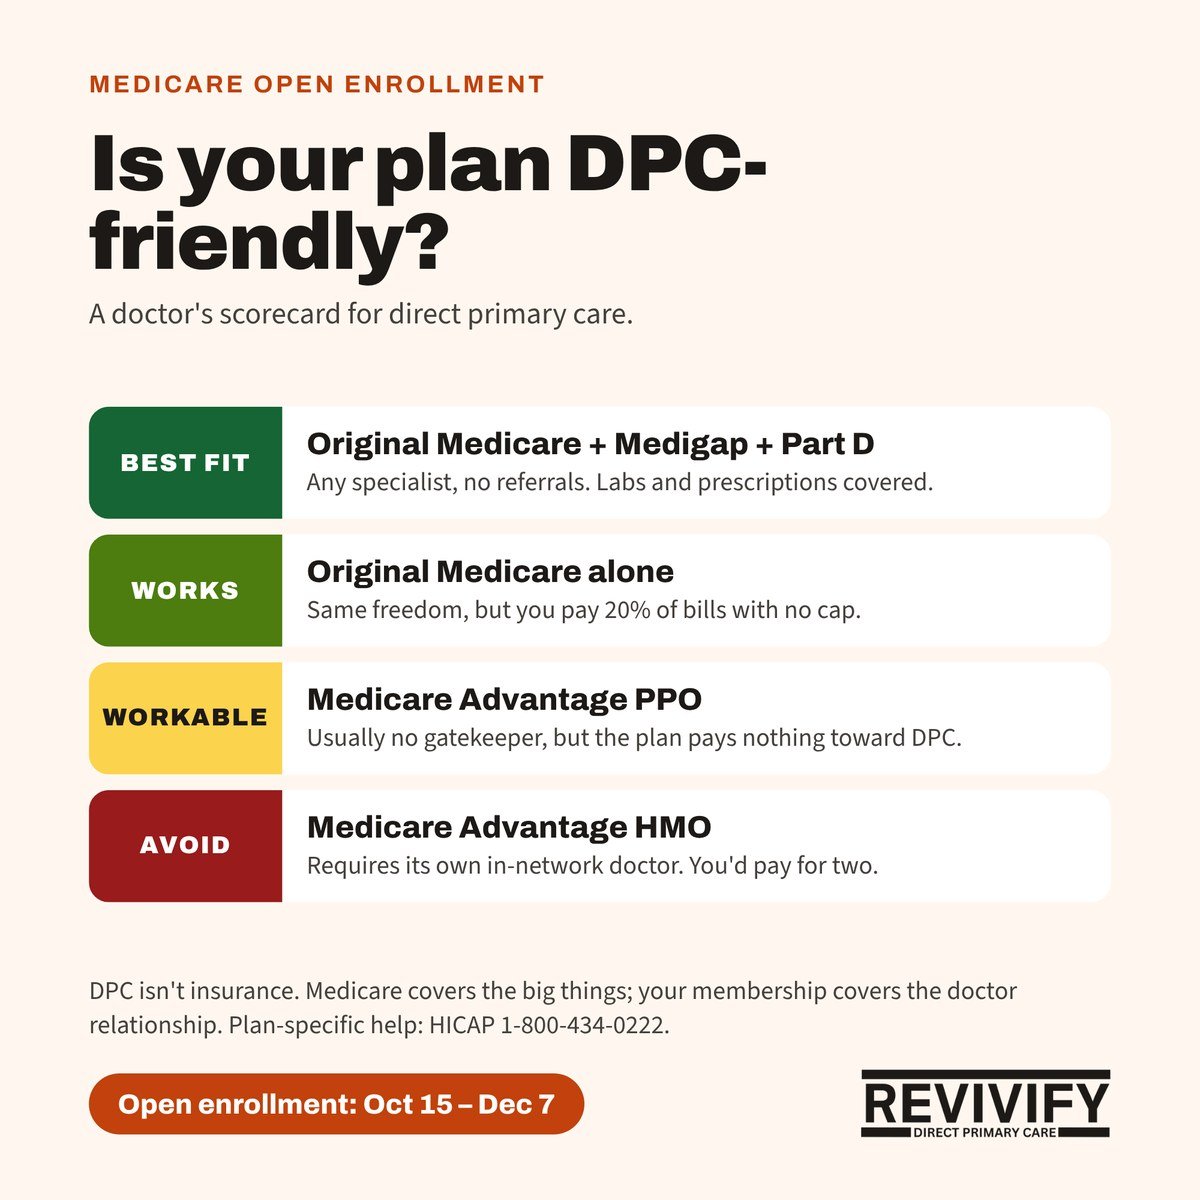
Open enrollment starts October 15. Somewhere right now, a perfectly smart 68-year-old is comparing two plans on a laptop, choosing between the one with the $0 premium and the one with the better dental coverage. Neither column on that comparison chart says what I’d want to know first: Will this plan let me have a doctor who actually has time for me?
That’s what this post is about. If you’re curious about direct primary care, here’s a straightforward scorecard of which Medicare setups work well with it, which ones work with some friction, and which one I’d steer you away from.
The Problem: Plan Comparisons Don’t Measure What Matters to You
Medicare’s Plan Finder and every insurer’s brochure compare premiums, deductibles, copays and drug costs. Those matter. But none of them measure how easy it will be to see the doctor you choose, or whether you’ll need permission to see a specialist.
For most people, that’s a background issue. For anyone who wants a direct primary care doctor, it’s the whole ballgame.
The Insight: DPC Isn’t Insurance, So the Question Is Compatibility
A quick refresher. Direct primary care is a flat monthly membership paid directly to your doctor. At Revivify, that’s $129 a month for unlimited visits, same or next-day appointments, visits that start at 30 minutes, and the ability to text or call me directly.
DPC doesn’t replace Medicare. You still need Medicare for hospitals, specialists, imaging, surgery and prescriptions. So the real question isn’t “DPC or Medicare?” It’s “Which Medicare setup plays nicely with DPC?”
One more piece of background: like many DPC doctors, I’ve formally opted out of Medicare. That means I don’t bill Medicare at all, and my Medicare patients sign a simple private contract acknowledging that. It’s what makes the flat membership possible. It also means no Medicare plan will pay me, which is fine, because the membership covers my care.
Green: Original Medicare + Medigap + Part D
This is the most DPC-friendly setup, and it isn’t close.
- No networks. You can see any specialist in the country who accepts Medicare. When I refer you to a cardiologist, you call and book.
- No referrals required. Original Medicare doesn’t need a gatekeeper’s permission, so you never need a second primary care doctor.
- Labs, imaging and therapy still covered. Medicare covers lab tests, imaging, physical therapy and medical equipment I order, as long as they’re done by Medicare providers.
- Prescriptions covered. Your Part D plan covers prescriptions I write.
- Predictable costs. Medigap covers most of what Original Medicare leaves behind. Your membership covers primary care. There’s very little left to surprise you.
The tradeoff: Medigap and standalone Part D cost more each month than many Medicare Advantage plans, and you give up Advantage extras like dental and gym memberships.
Green With a Caution: Original Medicare Without Medigap
Everything above still works. You keep total freedom of doctors and no referrals. The caution is financial: without a supplement, you pay 20% of most outpatient bills with no annual cap. One surgery or a cancer diagnosis can get expensive quickly. If you’re on Original Medicare without Medigap, it’s worth finding out whether you can add a supplement.
Yellow: Medicare Advantage PPO
Workable, with some friction.
- Pros: PPOs usually don’t require you to choose a primary care doctor or get referrals for most specialists, so my referrals and orders typically work.
- The catch: a PPO’s out-of-network benefit only applies to doctors who haven’t opted out of Medicare. That means your plan pays nothing toward my care. Your membership does.
- The fine print: some PPO plans still want certain requests, like prior authorizations, to come from a named primary care doctor. Check your plan’s Evidence of Coverage before you commit.
Red: Medicare Advantage HMO (Including HMO-POS)
This is the setup I’d steer DPC members away from.
- You must choose an in-network primary care doctor. I can’t be that doctor.
- Specialist visits usually need that doctor’s referral. Some insurers are tightening this. UnitedHealthcare began requiring primary care referrals before certain specialist visits for most of its Medicare Advantage HMO and HMO-POS members in 2026.
- My orders may not be honored. An HMO generally won’t pay for care outside its network, and some won’t cover tests or referrals ordered by an out-of-network doctor.
The result: you’d pay my membership and keep an HMO doctor just to sign referrals. Two primary care doctors, one patient, and a lot of phone calls. We’ll go deeper on this next.
What Changes, and What Doesn’t, When You Join DPC
- Doesn’t change: your hospital coverage, specialist coverage, imaging, surgery, physical therapy and prescriptions. Medicare still handles those.
- Does change: your primary care visits, which come through your membership instead of Medicare. That means no copays at my office, longer visits, and direct access.
- Worth knowing: flu, COVID and pneumonia vaccines are covered under Part B at your pharmacy at no cost to you, so I usually send patients there for those.
Who This Is For
This scorecard is for anyone on Medicare who wants more from primary care than a seven-minute visit, and anyone helping a parent sort out their options this fall. It’s especially important if you’re in a Medicare Advantage HMO today and have been thinking about DPC.
FAQ: “Should I Switch?”
That depends on your health, budget and priorities, and I can’t pick a plan for you. What I’d suggest: if DPC appeals to you and you’re in an HMO, get a Medigap quote before December 7, then talk it through with HICAP (California’s free Medicare counseling, 1-800-434-0222) or a licensed broker. If a supplement is available at a price that works, the switch tends to be smooth.
The Revivify Difference
I limit Revivify to 300 members so every one of them gets real time. For Medicare patients, that includes help coordinating the parts of your care Medicare covers: finding the right specialist, getting labs done at the best price, and making sense of results.
What’s Next
Open enrollment runs from October 15 through December 7. Next up: the biggest myth about Medicare Advantage HMOs and DPC. If you’d like to talk through how DPC would work with your coverage, learn about our membership or call us at 858-429-0099.
This post is for general education and isn’t insurance advice. Revivify doesn’t sell insurance, and direct primary care is not insurance.
← Back to all posts